Listen to this article
Underwriting has never been short on information. The challenge is getting the right information in front of the right person at the right time.
A submission can involve multiple documents, supporting evidence, policy records, and underwriting guidelines, all of which need to be reviewed before a decision can be made. For underwriters, a significant part of the working day can therefore go into finding, validating, and organizing information rather than actually evaluating risk.
That is where insurance underwriting modernization needs to start: with the work surrounding the underwriting decision.
The goal isn't simply to process more submissions faster. It is to remove operational friction so experienced underwriters can spend more of their time evaluating risk, applying their expertise, and making informed decisions.
What should underwriters stop spending time on?
Underwriters should spend less time on repetitive document handling, information retrieval, workflow routing, and policy searches, and more time on activities that require underwriting judgment.
Many underwriting processes have already been digitized in some form. Yet digitization does not automatically eliminate the work that slows the process down.
Manual document handling, fragmented information, repetitive administrative tasks, and policy searches can continue to create bottlenecks even when the underlying systems are digital.
The practical opportunity is to look at these activities individually and ask a simple question: What is taking an underwriter's time that doesn't actually require underwriting judgment?
Where should underwriting workflow automation start?
Submission processing, document handling, and workflow routing are good places to start.
Automating these activities can reduce repetitive work and help move submissions through the process more efficiently, allowing underwriters to focus on evaluating the risk itself.
This is where underwriting workflow automation can address some of the operational work surrounding the decision without changing who makes the decision.
But operational automation is only one part of the equation.
How can AI underwriting support better risk assessment?
Risk assessment often means bringing together information scattered across multiple documents. An underwriter may have to review supporting evidence, identify relevant details, and synthesize those findings before reaching a decision.
AI-assisted document analysis can help with this work by summarizing relevant information and highlighting important risk factors. The technology supports the underwriter's assessment rather than replacing underwriting expertise or final authority.
This is an important role for AI underwriting: helping underwriters access and interpret relevant evidence more efficiently while keeping the final assessment with the person responsible for the decision.
That can make a meaningful difference when the objective is not simply faster processing, but more consistent access to the information needed to make a decision.
Our playbook's documented results illustrate the potential. Its internal underwriting operations analysis reports 20% faster underwriting, attributed to improved access to relevant underwriting information and reduced manual document review. It also reports a 15% improvement in underwriting consistency, associated with more standardized risk assessment.
Why does policy verification matter in underwriting?
Policy verification is another overlooked opportunity.
When underwriters need to search across policy documentation and confirm that policy language aligns with underwriting rules, manual searches can add time to the process and create room for inconsistent interpretation.
Policy verification software can make this process more direct by helping underwriters locate relevant guidance and validate policies against existing standards.
According to our playbook, the approach has demonstrated 20–25% faster policy verification, driven by AI-assisted validation and intelligent policy document search.
The broader point is important. Faster verification isn't valuable simply because a clock moves faster. It matters because reducing the effort required to find and validate information can free underwriters to concentrate on the decisions that require their expertise.
What does underwriting decision support look like in practice?
Underwriting decision support is about making the information needed for a decision easier to access, review, and interpret, not about removing the underwriter from the process.
That means bringing together relevant evidence, reducing manual searches, supporting policy verification, and limiting repetitive administrative work around the decision.
The result is a workflow in which technology supports the operational and information-intensive parts of underwriting while experienced underwriters continue to apply judgment, expertise, and governance.
What should insurers measure beyond underwriting speed?
Modernization also changes how underwriting performance should be measured.
Turnaround time remains important, but it is only one part of the picture. Insurers should also look at manual effort per submission, decision consistency across teams, policy verification accuracy, operational efficiency, and customer responsiveness alongside speed.
That creates a more useful definition of progress.
An underwriting operation that processes work faster but still depends heavily on manual searches and produces inconsistent outcomes hasn't necessarily addressed the underlying problem.
When automation, decision support, and policy verification work together, that’s when modernization becomes more meaningful.
What does a practical underwriting modernization approach look like?
Insurers don't need to transform everything at once.
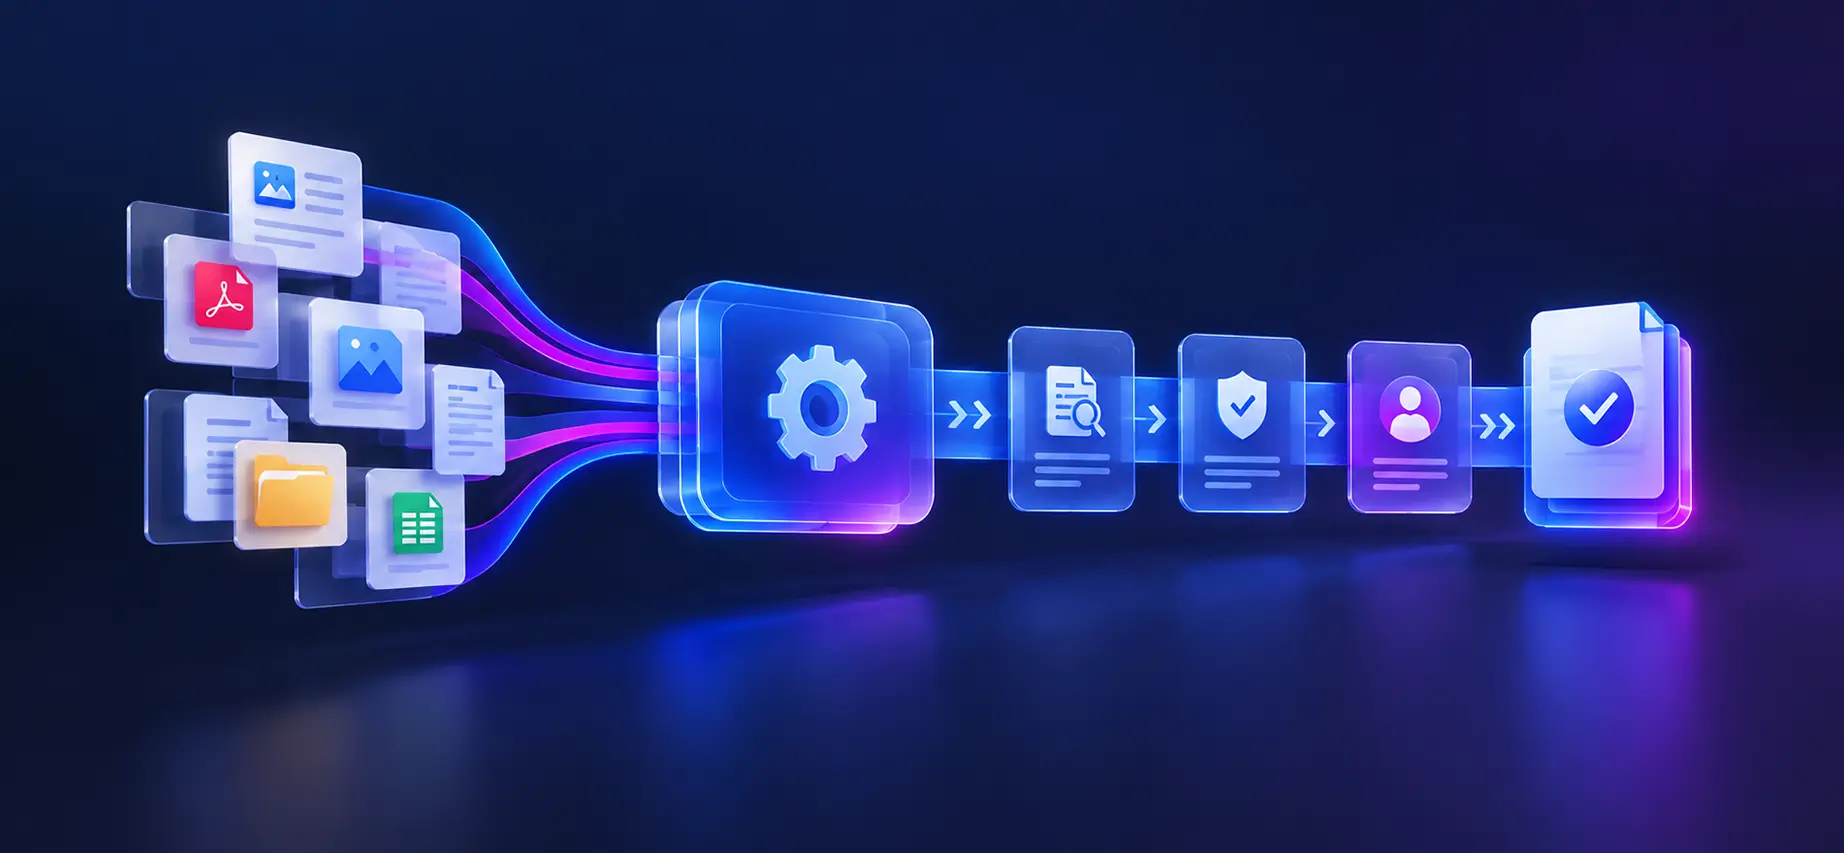
A practical approach is to first automate repetitive operational work, then improve underwriting intelligence, standardize policy verification, and continuously optimize performance.
Each stage builds on the previous one. The objective is to progressively remove friction from the underwriting process while preserving the expertise, governance, and judgment that good underwriting depends on.
The question, therefore, is not simply how much of underwriting can be automated. It is where automation and technology can remove work that does not require underwriting judgment, giving experienced underwriters more time to focus on the decisions that do.
Read the full Modern Underwriting Playbook to explore the four-stage modernization approach, the key underwriting opportunities, measurement framework, and documented operational outcomes in greater detail.
Ready to move from insight to action?
Whether you’re exploring new opportunities, solving operational challenges, or planning your next stage of growth, Visionet can help you move forward with clarity and confidence.
Speak with our experts to explore how we can support your business goals.
