Listen to this blog
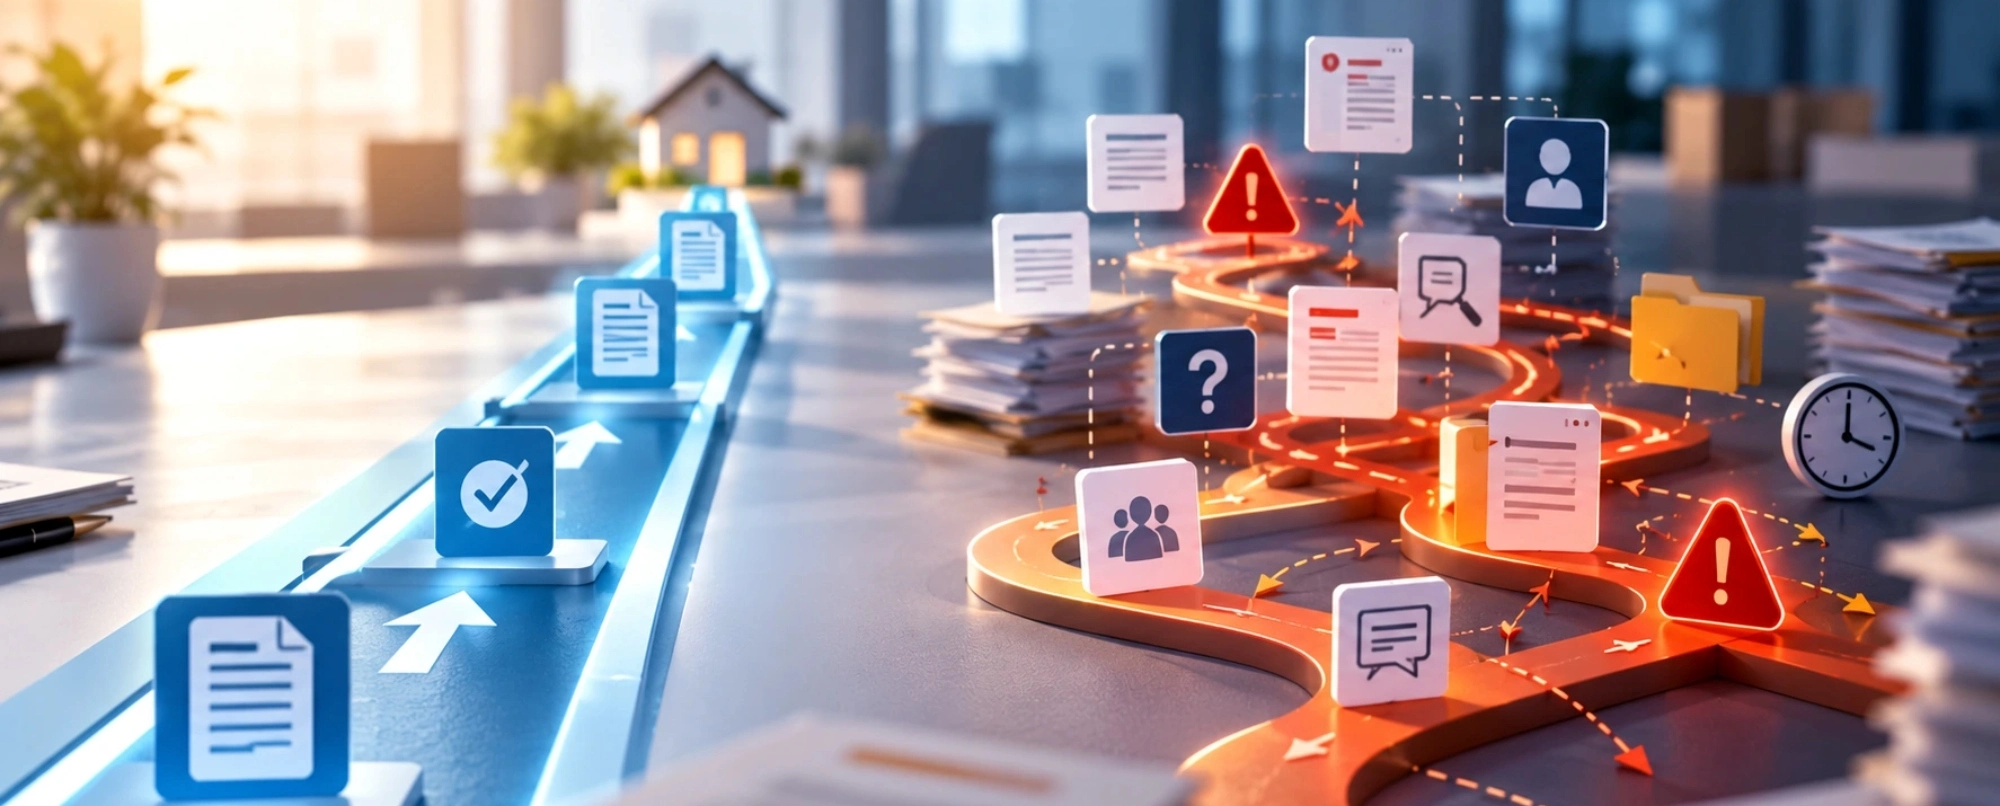
Most mortgage processes look impressive when everything goes according to plan. Documents arrive when expected, data agrees across sources, the borrower responds quickly, ownership is obvious, and each team completes its part before handing the file forward. The loan keeps moving, the workflow behaves as designed, and there is little reason for anyone to intervene.
That is the happy path, and it is also where operations are least likely to fail. The real test begins when something does not fit. An income source is unusual, two documents tell slightly different stories, a borrower’s circumstances change midway through processing, or a file that should have followed the standard route suddenly needs judgment, clarification, or escalation. At that point, the process can change character completely. What had been a structured workflow becomes a series of manual checks, messages, callbacks, exceptions, and decisions about who should do what next. A file that moved smoothly for days can suddenly stall because nobody is quite sure which path it belongs on, and that is where predictability starts to disappear.
Exceptions are not edge cases in mortgage operations
Mortgage lending is full of variation. Borrowers do not all earn income the same way, documents are not always complete, information changes, and some files involve circumstances that cannot be resolved through routine processing alone. None of this is unusual, yet many operating models are still built as though the standard file is the process and everything else is an interruption to it.
That distinction matters because, when exceptions are treated as occasional disruptions, teams are forced to improvise whenever a loan moves outside the normal route. Someone has to decide who owns it, another person determines whether it requires escalation, additional information is gathered, and managers may become involved simply to establish what should happen next. The more complicated the case, the greater the chance that progress depends on individual experience rather than a clearly designed operating model.
Over time, this can create two mortgage processes inside the same organization. There is the formal process that works well for straightforward files, and then there is the informal process experienced employees use to navigate everything else. The first is visible in workflows, procedures, and reporting. The second is often where much of the operational risk sits.
A difficult file should not become an operational black hole
Complexity does not have to mean loss of control. A stronger operating model anticipates that some files will need a different path and makes that path explicit. Teams should know when an issue becomes an exception, who owns the next action, what information is needed to resolve it, and when escalation is appropriate.
Clear escalation paths can prevent files from bouncing between teams, while defined ownership reduces avoidable waiting time. Better visibility allows managers to see which loans have moved outside the normal flow and why, and structured decision rules make routine exceptions easier to resolve without turning every unusual circumstance into a management issue. These controls do not remove judgment from mortgage operations. They make it easier to apply judgment where it is genuinely needed.
That distinction is important because experienced professionals should spend their time interpreting complex situations and making informed decisions. They should not have to spend a significant part of that time figuring out who needs to be involved, reconstructing how the file reached its current state, or deciding where responsibility sits. The better the exception process, the less operational energy is wasted simply organizing the response.
Predictability is tested when the standard process stops working
It is easy to measure the speed of clean files because they move quickly, generate fewer questions, and fit neatly into existing workflows. But clean files do not reveal much about the resilience of an operation. Difficult files do. They expose weak ownership, reveal where escalation paths are unclear, and show whether teams have enough visibility to understand what is happening. They also reveal whether operational knowledge is embedded in the process or held by a small number of experienced individuals.
This is where Visionet BPS can help mortgage organizations rethink the operating model. The opportunity is not simply to make the happy path faster, but to design workflows, ownership structures, and operational controls that continue to function when a file no longer behaves exactly as expected. That creates a different kind of performance improvement. Instead of optimizing only for speed, the organization improves its ability to absorb variation without losing visibility or control.
Exception-heavy files become easier to manage, escalations become more purposeful, managers spend less time rescuing individual loans, and teams gain greater confidence about what happens next. The result is not an operation with fewer difficult files, because mortgage lending will always have those. It is an operation that can handle difficulty without immediately becoming unpredictable.
That is the standard worth designing for. The real test of mortgage operations is not how smoothly the easy loans move through the system, but how calmly, consistently, and deliberately the organization responds when they do not.
Ready to move from insight to action?
Whether you’re exploring new opportunities, solving operational challenges, or planning your next stage of growth, Visionet can help you move forward with clarity and confidence.
Speak with our experts to explore how we can support your business goals.