Listen to this blog
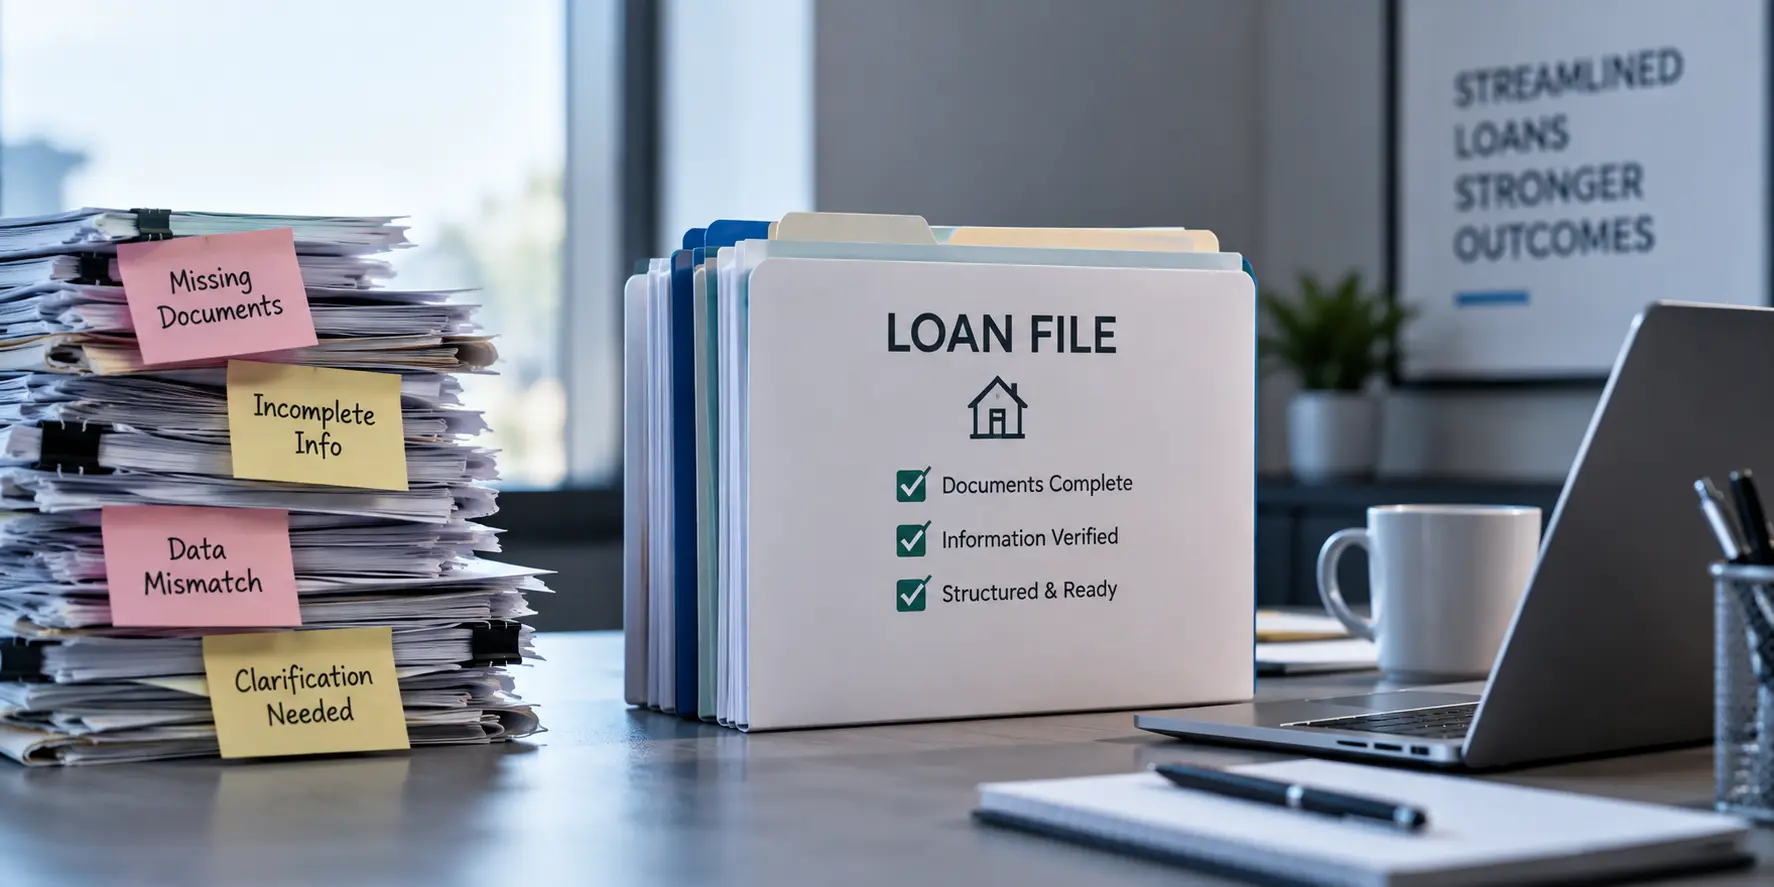
Imagine a processor opening a new loan file. Before any meaningful processing can begin, they discover that the documents are poorly organized. A key item is missing. Information does not reconcile. Another document is present but unclear. The processor has not even started the work they were supposed to do, yet they are already fixing the file.
That distinction matters. Highly trained mortgage professionals are expensive resources. Yet across many operations, a surprising amount of their time is spent preparing work that should have arrived ready for them. They sort documents, validate data, clarify inconsistencies, and chase missing information before meaningful work can even begin. Only after that can the actual job start.
The first human touch is already costing you
File quality is often treated as an administrative concern, while processing speed receives much more attention. How quickly can the processor complete the review? How can underwriting turnaround time be reduced? How can more loans move through the same team? Those are sensible questions, but they start too late.
If a processor receives an incomplete or poorly structured file, part of their capacity has already been lost before the clock on meaningful processing should even have started. The same problem then travels downstream. An unresolved inconsistency may reach underwriting. A missing item may trigger a new request. Updated information may require calculations to be checked again. Quality review may expose something that should have been identified much earlier. The later a basic file issue is discovered, the more people it is likely to involve.
Preparation changes the economics of the workflow
That is why file readiness deserves as much attention as processing speed. A clean file behaves differently. The required documents are present. Information is structured. Obvious inconsistencies have been surfaced. The next team can understand what it has received and begin useful work immediately.
This does not eliminate every exception. Mortgage lending will always involve judgment, unusual borrower situations, and information that changes during the lifecycle. The objective is not perfection. It is to stop using skilled operational capacity on preventable preparation work.
When that happens, processors can spend more time progressing files, underwriters can focus on decisions, and quality teams can focus on meaningful risk rather than defects that should have been caught earlier. The value accumulates throughout the lifecycle.
Speed after intake cannot compensate for poor readiness
There is a natural temptation to solve productivity problems by asking people to move faster. But speed has limits when the inputs themselves are inconsistent. A processor cannot efficiently advance a file that is missing critical information. An underwriter cannot make a confident decision from contradictory data. A quality reviewer cannot avoid raising exceptions simply because a closing deadline is approaching.
The real opportunity is to improve what reaches each team in the first place. Strong intake governance creates clearer standards around what enters production. Structured readiness checks identify obvious gaps before work progresses. Disciplined workflow design helps prevent files from moving simply because the previous step has been marked complete.
The distinction is subtle but important. Completion asks whether somebody performed the task. Readiness asks whether the file is genuinely prepared for what happens next. Mortgage operations become much more predictable when the second question drives movement.
Put expertise where it creates value
This principle sits at the heart of Visionet’s BPS approach. The goal is not simply to process tasks faster. It is to structure mortgage workflows so that experienced professionals spend less of their day repairing preventable issues and more of it progressing loans. That requires attention at the front of the process through better intake controls, clearer workflow discipline, and consistent readiness checks before a loan moves deeper into operations.
For lenders under pressure to improve productivity without continually expanding headcount, that can create a very different capacity equation. Instead of asking how many additional people are required to absorb growing workloads, leaders can first examine how much skilled capacity is currently being consumed by avoidable file preparation and correction. Sometimes the answer is substantial.
Once a weak file moves through several stages, every correction carries more context, more coordination, and more operational effort. Solve the issue before the first meaningful touch, and the disruption may never enter the workflow. That is the larger lesson. Better preparation is not administrative housekeeping. It is an operating model decision.
When lenders are trying to improve throughput, protect margins, and make better use of experienced teams, preparing work properly can deliver more value than simply asking everyone to process it faster. Sometimes the biggest productivity improvement happens before processing begins at all.
Ready to move from insight to action?
Whether you’re exploring new opportunities, solving operational challenges, or planning your next stage of growth, Visionet can help you move forward with clarity and confidence.
Speak with our experts to explore how we can support your business goals.
